Five lessons on mobilising faith-based resources for sustainable development and turning them into scalable investment.
With development assistance under pressure, faith-based assets and giving could play a greater role in financing sustainable development. But unlocking their potential requires more than mobilising money. It calls for credible financial structures, shared standards and partnerships that connect faith-based resources with development finance institutions. Drawing on discussions at the PaRD Annual Forum 2026 in Bangkok, Dr Jubril Adeojo outlines five key takeaways and proposes a practical way forward, starting with pilot projects in Nigeria.
From fragmented assets to finance for sustainable development
Faith actors have long mobilised resources to support communities, provide essential services and respond to social needs. Their contributions extend beyond donations to include land, endowments, regular giving and other assets held for charitable purposes. Yet much of this capital remains fragmented, limiting its potential to contribute to development at scale.
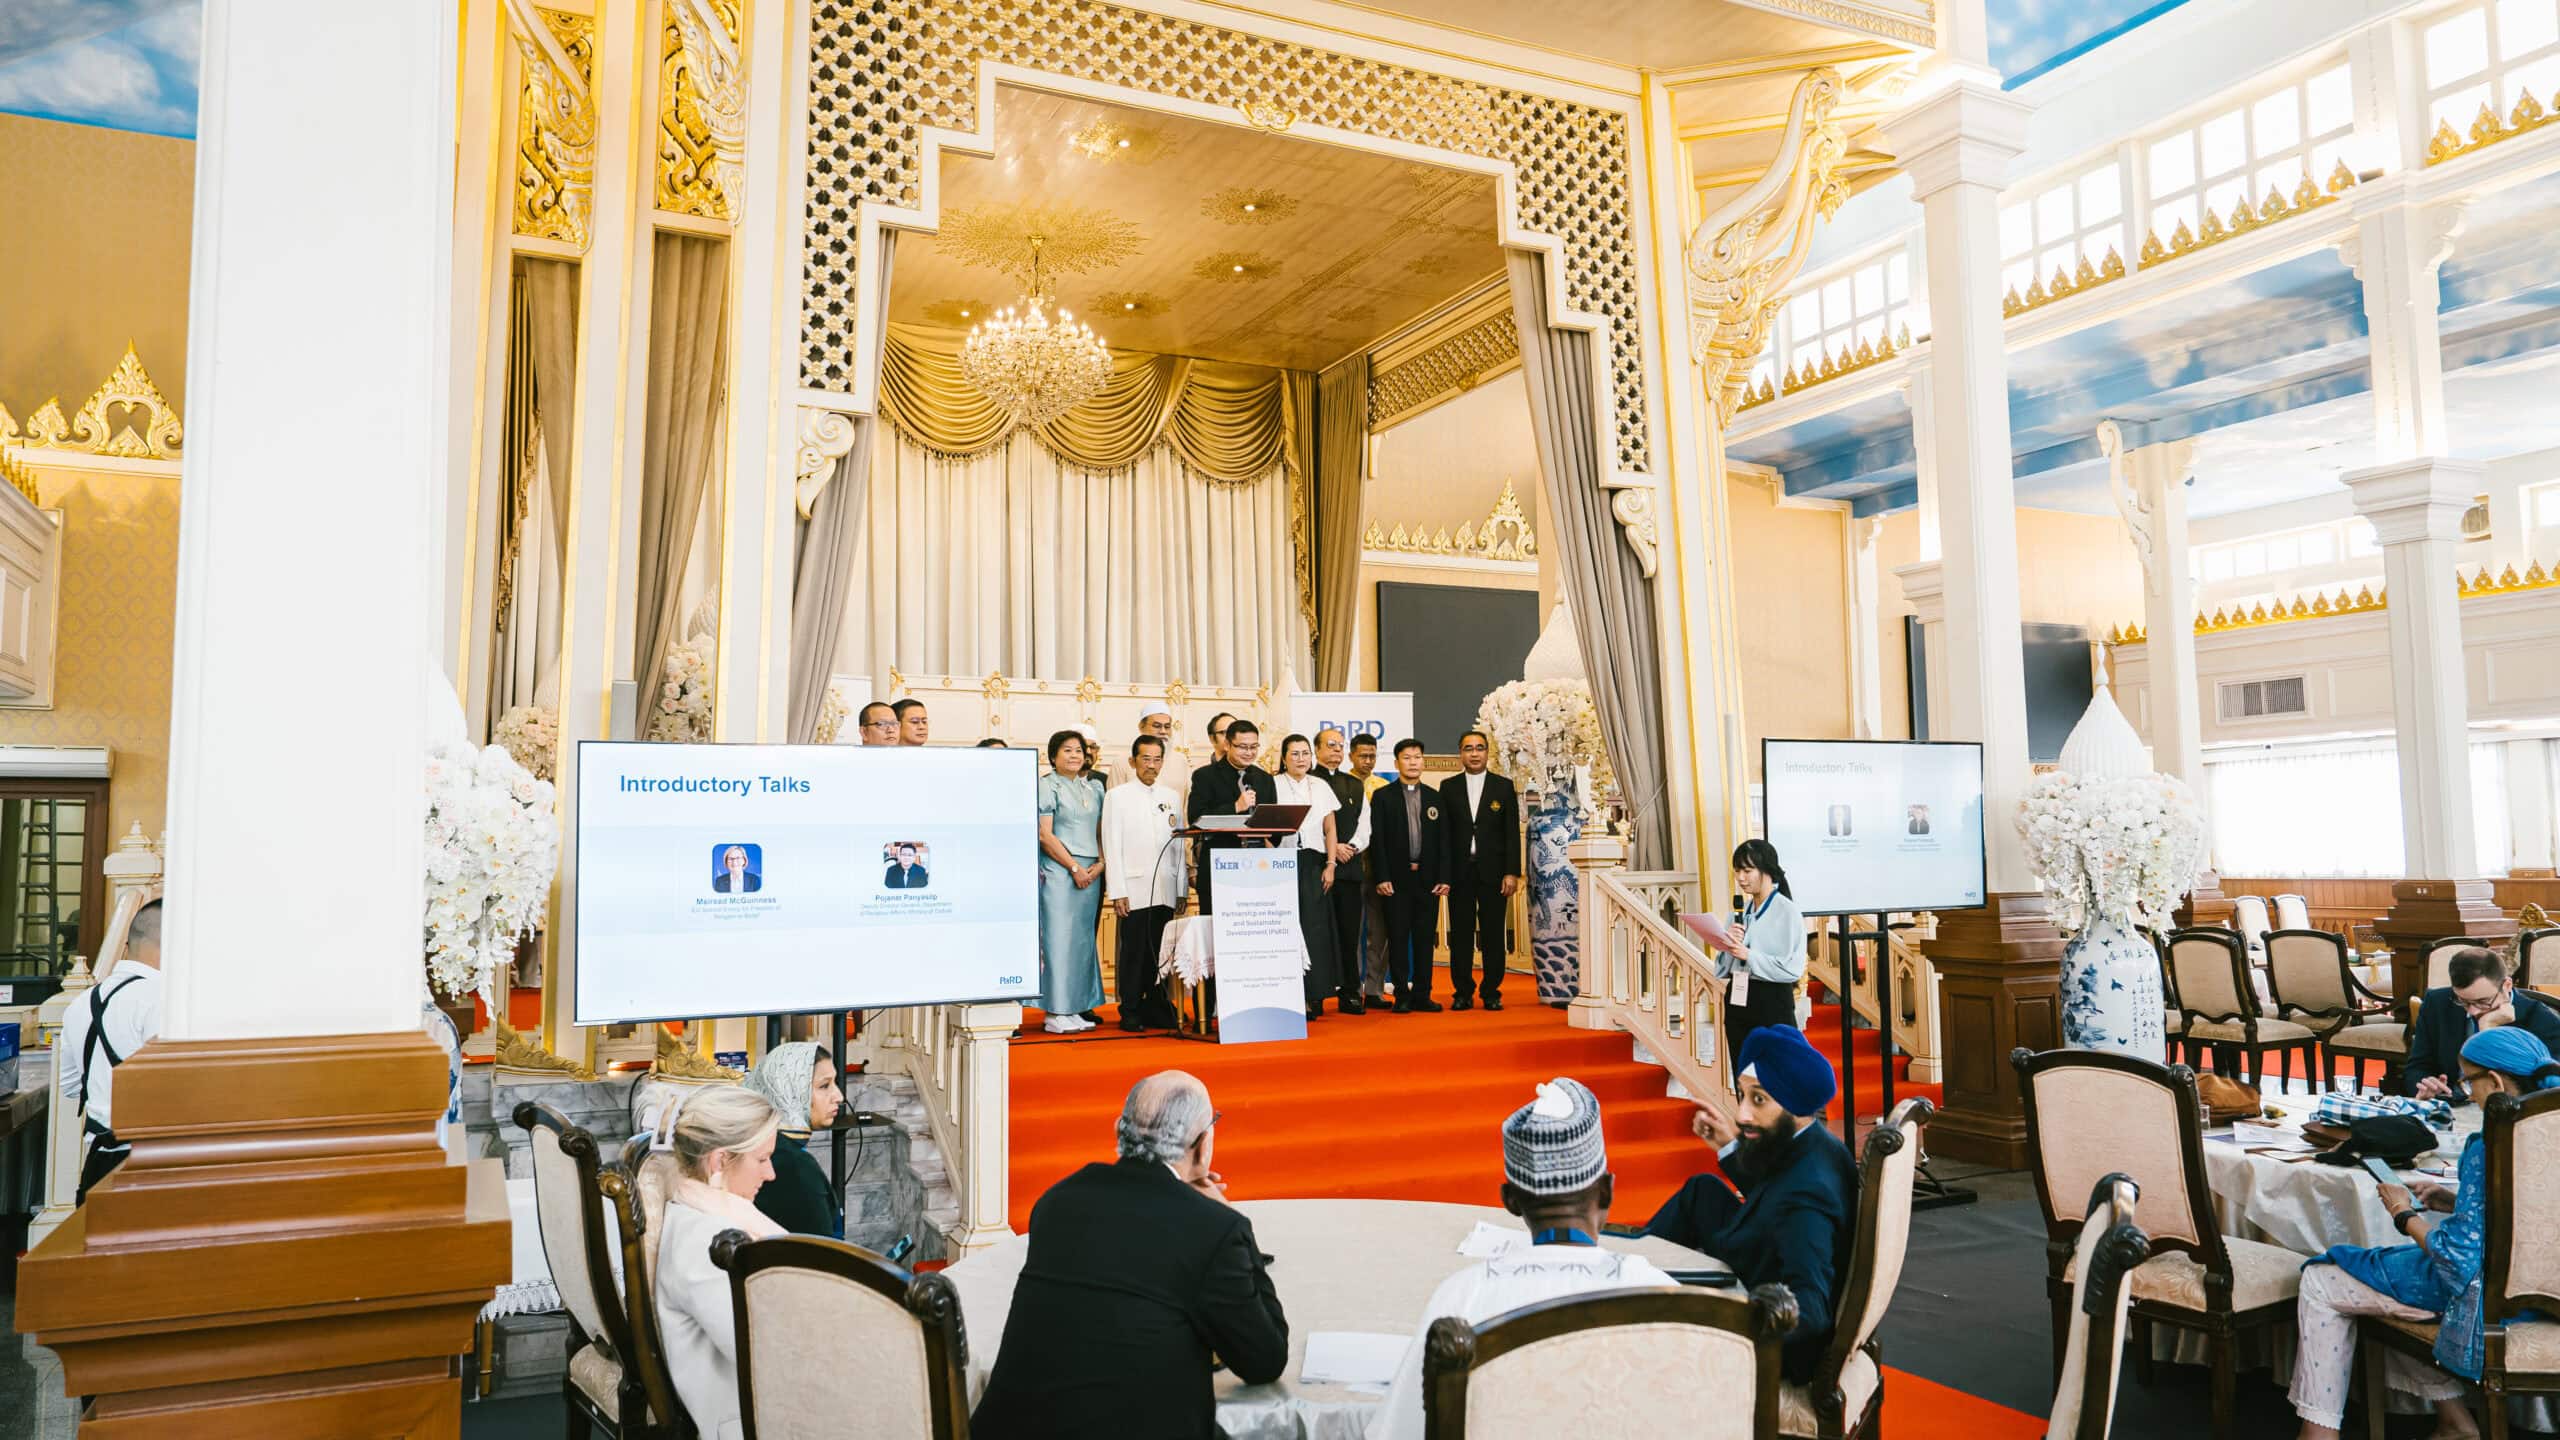
Discussions at the PaRD Annual Forum in Bangkok highlighted an opportunity to connect these resources more systematically with development finance. With official development assistance under pressure, the question is how faith-based capital can complement public funding, development finance institutions (DFIs) and private investment while remaining true to its underlying values and purposes.
Five key lessons
First, faith traditions already offer principles that align with responsible investment. Stewardship, risk-sharing and the avoidance of harm are embedded in many religious and ethical traditions. Rather than developing an entirely new ethical framework, the task is to translate these principles into practical investment standards, governance arrangements and accountability mechanisms.
Second, the main obstacle is structural rather than a lack of willingness among faith actors. Resources such as land, Islamic endowments known as waqf, zakat and Christian tithes and offerings are often managed separately. Connecting them with institutional finance requires suitable vehicles, clear governance, consistent standards and evidence of development impact that investors and DFIs can assess.
Third, faith-based capital could play a catalytic role in blended finance. By taking positions in technical assistance, first-loss facilities, guarantees or junior financing, it could help address some of the risks that prevent other investors from participating. This could enable larger volumes of development and private capital to be mobilised alongside relatively limited faith-based contributions. Adeojo identifies leverage ratios of three to five times in pilot projects and up to ten times in a standardised, rated platform as potential targets, rather than established results.
Fourth, non-interest-based financial structures can offer opportunities for investors from different religious and ethical backgrounds. Instruments such as sukuk, waqf-linked funds, musharakah equity partnerships and qard hasan, an interest-free loan, can support different forms of investment and charitable financing. Their application depends on the relevant legal, financial and religious requirements. Nigeria’s first corporate green sukuk, issued by OWPPiN in 2021, provides a national example of how Islamic financial principles can be applied to green investment.
Fifth, credibility depends on evidence and accountability. Independent ethical and Shariah oversight, traceable use of funds and verified impact are essential to ensure that investments deliver on their stated purposes. Assessment should consider not only financial returns but also outcomes for people, communities and the natural environment. These safeguards can help prevent faith-washing, in which religious values are invoked without sufficient evidence that financial practices reflect them.
Building a practical framework
Turning these principles into investment opportunities requires structures that faith organisations and institutional investors can both understand and trust. Adeojo proposes a Catalytic Blended Impact Finance Facility Stack: a framework for faith-sponsored facilities with four complementary financing windows.
These would cover technical assistance to prepare projects, first-loss capital to absorb initial losses, junior or mezzanine financing to share risk, and co-financing to bring in additional investors. Together, the windows would provide a structured approach to preparing projects, allocating risks and mobilising further capital. The proposed framework would also establish common standards for governance, ethics, capacity development, impact measurement, reporting and learning.
A second element would be a set of Islamic and non-interest-based catalytic fund structures. Developed in collaboration with faith-based DFIs, banks, fund managers and religious organisations, these could include debt and equity instruments, sustainability-linked funds and infrastructure investment vehicles. The aim is to create options that accommodate different financial requirements while offering transparent terms and credible evidence of impact.
The third element is a pilot programme in Nigeria. Working with interested DFIs, non-interest and commercial banks, fund managers, churches and Muslim associations, the programme would test selected models in practice. The results could help identify which structures are viable, what conditions are needed for success and which approaches could be replicated elsewhere.
Giving PaRD a role in connecting partners
PaRD could help bring these elements together by convening faith actors, DFIs, the World Bank Group and other relevant partners around a shared programme. Its role could include facilitating dialogue between organisations that do not always share the same financial vocabulary, supporting the development of common standards and providing a platform for documenting lessons from pilot projects.
This mutual learning is important. Faith organisations may hold significant assets and have strong community relationships but lack the technical capacity or financial structures required to engage with institutional investors. Conversely, development financiers may need a better understanding of religious governance, charitable obligations and the conditions under which faith-based resources can be used.
A coordinated approach could help bridge these gaps while respecting the independence and purposes of participating organisations. Design-phase funding and technical partners would be needed to develop the proposed framework, assess potential projects and establish the governance and impact-measurement arrangements before implementation.
The ultimate test will be whether these structures can turn fragmented resources into reliable, measurable benefits for communities. Mobilising additional capital matters, but scale alone is not the objective. The goal is to ensure that faith-based resources complement wider development efforts, that risks and benefits are shared fairly, and that investments deliver lasting social and environmental outcomes.
The discussions in Bangkok provide a starting point. A structured facility framework, suitable fund models and carefully designed pilots in Nigeria could help move the conversation from potential to practice. With the right partners, standards and evidence, faith capital could become a more effective contributor to sustainable development.
About Prof. and ADB Institute
insert here description and links (use speaker docuemnt from Bangkok)